
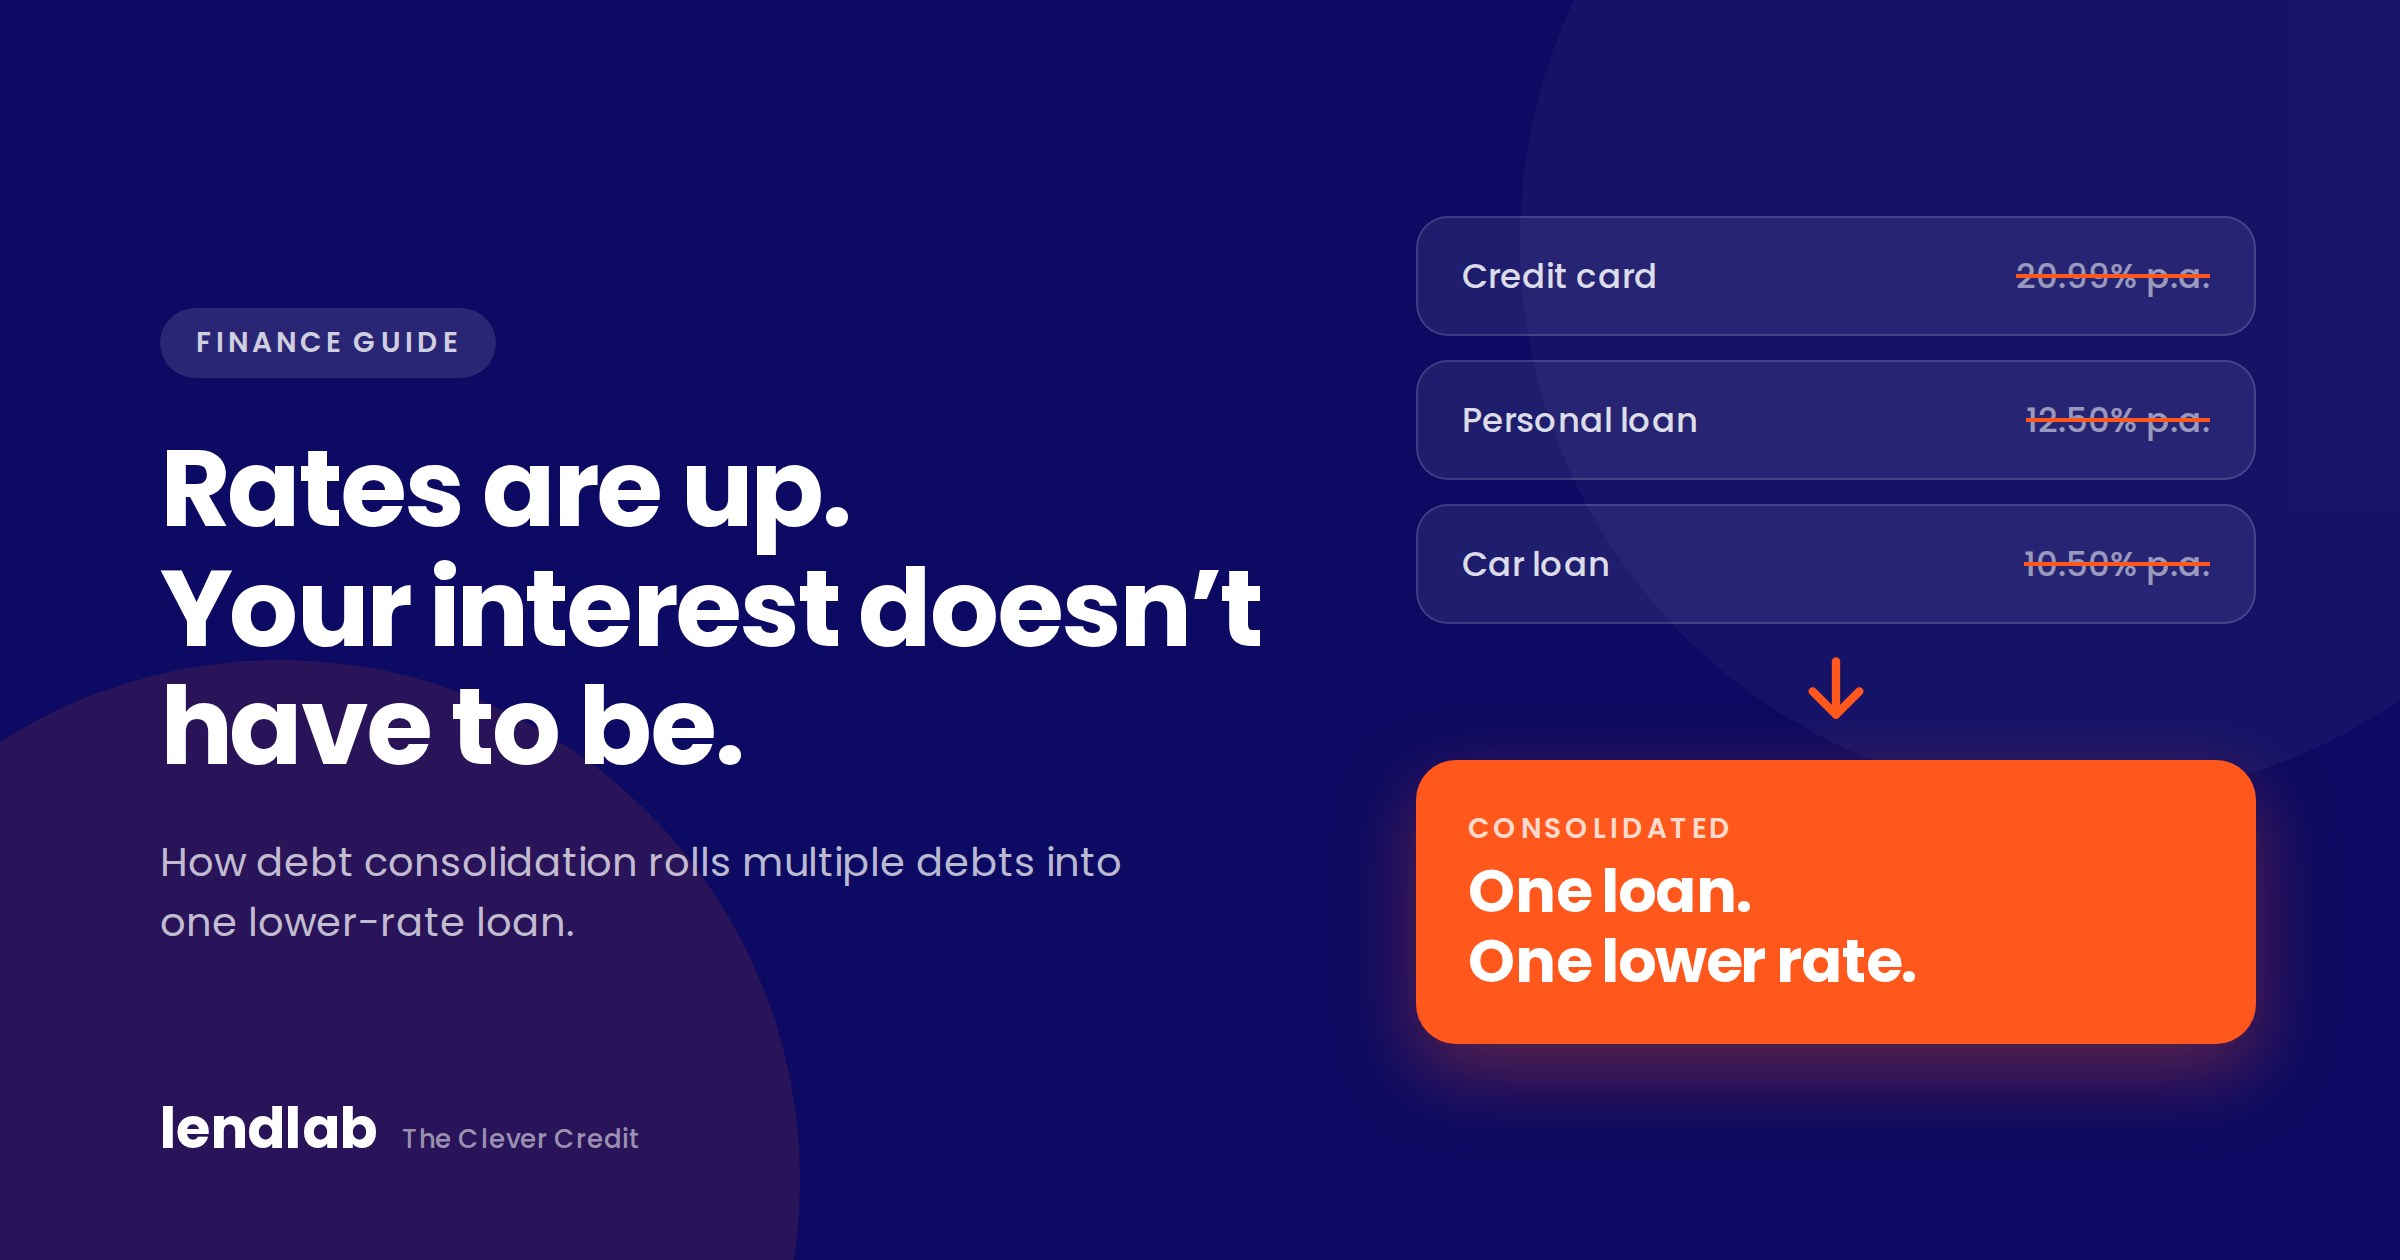
Your mortgage rate went up. So did groceries, insurance and power. If you also hold a credit card, a personal loan and a car loan, that's three or four separate debts, each charging its own rate, and each one costing you more than it needs to.
Smart borrowers don't just absorb rising costs. They restructure. Debt consolidation rolls those debts into one loan at one lower rate, so more of every repayment goes to clearing what you owe instead of feeding interest.
Why Your Debt Costs More in 2026
The Reserve Bank lifted the cash rate three times between February and May this year, taking it to 4.35%, and has been clear that more rises are possible while inflation stays sticky. Lenders have passed those increases straight on to borrowers.
Sources: RBA cash rate target history; Canstar analysis. Figures as at September 2026.
While your mortgage gets the headlines, it's often the smaller debts that cost the most. Credit cards commonly charge 20% p.a. or more, which makes them the most expensive money most people hold. Moving that balance to a lower rate is one of the simplest wins available.
"Four debts means four rates, four due dates and four lots of interest. One loan at a lower rate puts you back in control of what you pay."
What Is Debt Consolidation?
It's simple. You take out one new loan and use it to pay off your existing debts in full. Those accounts close, and you're left with a single loan, a single interest rate and a single repayment on a fixed schedule.
Common debts people consolidate include credit cards, store cards, buy now pay later balances, existing personal loans and car loans.
How It Can Ease the Pressure
A Lower Interest Rate
Swap 20%+ credit card rates for a single personal loan rate. With lendlab, unsecured rates start from 5.95% p.a. for strong applicants.
One Repayment, One Date
Swap multiple due dates across different lenders for one simple, automated repayment that's easy to track.
A Clear Finish Line
Credit cards have no end date. A consolidation loan has a fixed term, so you know exactly when you'll be debt-free.
A Budget You Can Plan Around
A predictable repayment makes it easier to plan for the bills that keep rising, and to see where every dollar is going.
What It Could Look Like: A Worked Example
Here's an illustrative example of someone carrying $35,000 across three debts, comparing the cost of clearing them over five years at their current rates versus one consolidation loan.
| Debt | Balance | Interest rate |
|---|---|---|
| Credit card | $12,000 | 20.99% p.a. |
| Personal loan | $15,000 | 12.50% p.a. |
| Car loan | $8,000 | 10.50% p.a. |
| Before: three debts | $35,000 | ~14.95% avg |
| After: one consolidation loan | $35,000 | 9.95% p.a. |
Illustrative only. Assumes all debts are repaid over the same 5-year (60-month) term with monthly principal and interest repayments: ~$832/month before, ~$743/month after. Excludes fees and charges. Your rate and savings will depend on your circumstances and credit profile.
Run Your Own Numbers
Pop in your own figures for a rough idea of what consolidating could save you. For your actual rate, get a 60-second quote below.
Estimate only, based on monthly principal and interest repayments over the same term. Excludes fees. Not a quote or an offer of credit.
Is Debt Consolidation Right for You?
It tends to work best if most of these sound like you:
- You have two or more debts, especially credit cards or store cards with high rates
- You want to pay less interest as rates and living costs rise
- You'd rather have one predictable repayment than several moving parts
- You have a steady income and a strong credit history
- You're happy to close the cards you pay off
When It Might Not Be the Answer
Consolidation works best when the numbers stack up, and a good broker will tell you when they don't.
- A longer term can cost more. Lower repayments over more years can mean paying more interest overall, even at a lower rate.
- Fees matter. Establishment fees and early exit fees on existing loans can eat into your savings. Always compare the total cost.
- Close what you clear. Keeping paid-off cards open with full limits can affect your borrowing power down the track.
How lendlab Makes It Simple
lendlab compares options across our lender panel to find the lowest rate available for your profile, so you're not stuck with what one bank offers.
- Get your quoteAnswer a few questions and see your options in 60 seconds, with no credit score impact.
- Compare your optionsSee real rates and repayments, with all fees already included.
- Work with your analystA dedicated analyst handles your file from quote to settlement.
- Clear your debtsYour old debts are paid out and you're left with one simple repayment.
Frequently Asked Questions
What is debt consolidation?
Debt consolidation means taking out one new loan to pay off several existing debts, such as credit cards, personal loans or car loans. You're left with one loan, one interest rate and one regular repayment.
Can debt consolidation lower my interest rate?
It can. If your new loan has a lower rate than the average across your current debts, you'll pay less interest. The biggest savings usually come from replacing high-rate credit card debt.
Will getting a quote affect my credit score?
Not with lendlab. Our 60-second quote uses a soft credit check, which has no impact on your credit score.
Is debt consolidation always cheaper?
Not always. Stretching debt over a longer term can mean paying more interest overall, and fees can reduce savings. It works best when the new rate is lower, the term is sensible and you close the cards you pay off.
You Might Also Find These Useful
Save Money with lendlab: A Guide to Debt Consolidation Loans
A closer look at how debt consolidation loans work and what you'll need to apply.
Good Credit, Financial Confidence & the Best Available Rates — That's Who lendlab Is Built For
Find out what makes a strong loan application and how to access the sharpest rates.
See What You Could Save in 60 Seconds
Get your personalised debt consolidation options, all fees included, with zero credit score impact.
Get a Free Quote → The Clever Credit · Unsecured rates from 5.95% p.a.This article is general information only and does not take into account your objectives, financial situation or needs. Consider whether it's right for you and read the relevant terms before applying. Worked examples and calculator results are illustrative estimates, exclude fees and charges, and are not an offer or approval of credit.
Rates from 5.95% p.a. (unsecured). Comparison rate [X.XX]% p.a.* *Comparison rate calculated on a [$30,000] unsecured loan over a [5]-year term. WARNING: This comparison rate is true only for the examples given and may not include all fees and charges. Different terms, fees or other loan amounts might result in a different comparison rate. Credit criteria, fees and charges apply.
lendlab · Australian Credit Licence 392616