
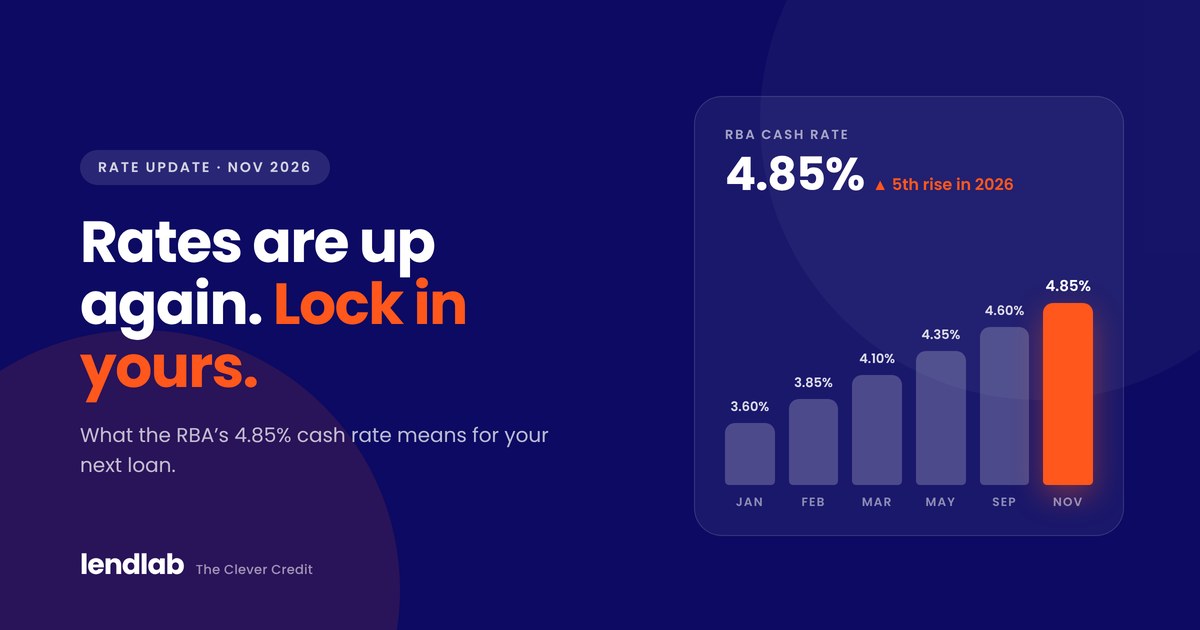
Five rate rises in eleven months. On Tuesday 3 November, the Reserve Bank lifted the cash rate by another 0.25 percentage points to 4.85%, its highest level since 2008. If you're planning a car, a big purchase or tidying up existing debt, the way you borrow from here matters more than ever.
Here's what happened, what the experts expect next, and the moves smart borrowers are making right now.
What Happened on Melbourne Cup Day
The RBA's Monetary Policy Board raised the cash rate from 4.60% to 4.85%. It wasn't unanimous. Six members voted for the increase and three preferred to hold, a sign some of the Board is growing more concerned about the slowing economy, housing and jobs.
Here's how 2026 has played out:
- Feb3.85%
- Mar4.10%
- May4.35%
- Sep4.60%
- Nov4.85%
The cash rate started 2026 at 3.60%. That's a 1.25 percentage point rise this year. Source: Reserve Bank of Australia.
Why the RBA Moved Again
In one word: inflation. The RBA now expects headline inflation to peak at 4.5% in the December quarter and stay above 3% until late 2027. It doesn't expect inflation to settle back at the middle of its 2–3% target until around mid-2028.
Higher fuel and commodity prices linked to the Middle East conflict are part of the story. The RBA is also worried about capacity constraints at home, weak productivity and rising inflation expectations. Its message is clear: demand needs to slow before prices do.
What Happens Next?
CommBank's economists believe this could be the last rise for now. They expect the RBA to hold at 4.85% in December while it watches the incoming data. They're forecasting two cuts in August and November 2027, which would take the cash rate back to 4.35%. They're also clear that the timing is uncertain.
"The risk remains the need for further tightening of monetary policy in 2027."
Belinda Allen, CommBank Head of Australian Economics
Translation: rates may have peaked, but they're not falling any time soon, and another rise isn't off the table if inflation surprises again.
What It Means for Your Budget
For a typical mortgage, the extra repayments add up fast. Here's an illustrative example, assuming lenders pass each rise on in full:
Illustrative only. Assumes a $600,000 principal and interest loan over 25 years with a variable rate of 5.60% p.a. at the start of 2026, rising by the full 1.25 percentage points.
That's money that would otherwise go toward your car, your savings or your next big goal. It's why the way you structure any new borrowing has never mattered more.
Five Smart Moves for Borrowers Right Now
- Lock in certainty with a fixed rate. Most car loans and many personal loans are fixed. Once your loan settles, your repayment stays the same, no matter what the RBA does next.
- Don't wait for cuts that may be a year away. Economists don't expect relief before late 2027. Waiting can mean paying more for the car or asset you need today.
- Consolidate high-rate debt. Credit cards and variable debts get more expensive with every rise. Rolling them into one fixed-rate loan can cut what you pay and give you a clear end date.
- Get pre-approved before you shop. Knowing your budget and rate up front puts you in a stronger position to negotiate.
- Compare, don't settle. One lender's offer is just one offer. A broker compares across a whole panel to find the sharpest rate for your profile.
The Secured Personal Loan
Our new Secured Personal Loan gives you secured pricing with the freedom of a personal loan. The funds go straight into your own account, not the dealer's. You can shop and negotiate like a cash buyer, with the sharper rate that comes from using an asset as security.
Check your rate →Find Your Best Rate in 60 Seconds
lendlab's quote portal compares loan options across our lender panel, negotiates on your behalf and shows you multiple options side by side, with all fees included. You can filter by your goal, whether that's the lowest rate or the lowest repayment. Your quote uses a soft credit check, so there's no impact on your credit score.
It's the same technology that helped lendlab founder Michelle Gorsevski become Australia's number one asset finance broker in The Adviser's Elite Broker Ranking 2026.
Frequently Asked Questions
What is the RBA cash rate in November 2026?
The RBA cash rate is 4.85%, after a 0.25 percentage point increase on 3 November 2026. It's the fifth rise of 2026 and the highest level since 2008.
Will interest rates go up again?
CommBank economists expect the RBA to hold rates at 4.85% in December. They say another rise in 2027 remains a risk if inflation surprises on the upside, and they're forecasting cuts in August and November 2027.
Does an RBA rate rise affect my car loan?
If your car loan has a fixed rate, which most do, your repayments won't change after a rate rise. New loans may be priced higher as lenders adjust, which is why comparing rates matters.
Should I wait for rates to fall before buying a car?
Economists don't expect cuts until at least August 2027, and the timing is uncertain. Many buyers choose to lock in a competitive fixed rate now rather than wait. A quick quote will show you where you stand, with no impact on your credit score.
You Might Also Find These Useful
Rates Are Up, Costs Are Up — How Debt Consolidation Can Take the Pressure Off
Roll multiple debts into one lower-rate loan with one repayment.
Michelle Gorsevski Named Australia's #1 Asset Finance Broker 2026
$58.6M settled across 1,859 loans, the most of any broker in the country.
Rates Are Up. Lock In Yours.
Compare fixed-rate car and personal loans across our lender panel in 60 seconds, with zero credit score impact.
Get a Free Quote → The Clever Credit · Rates from 5.95% p.a.Cash rate information is sourced from the Reserve Bank of Australia. Economic forecasts are from CommBank Global Economic and Markets Research (3 November 2026) and the RBA's November 2026 Statement on Monetary Policy. Forecasts may change and are not guaranteed. Mortgage repayment examples are illustrative only and lendlab does not arrange home loans.
This article is general information only and does not take into account your objectives, financial situation or needs. Rates from 5.95% p.a. Comparison rate [X.XX]% p.a.* *Comparison rate calculated on a [$30,000] [secured/unsecured] loan over a [5]-year term. WARNING: This comparison rate is true only for the examples given and may not include all fees and charges. Different terms, fees or other loan amounts might result in a different comparison rate. Credit criteria, fees and charges apply.
lendlab · Australian Credit Licence 392616